Categories
Real Estate Advice, Buyer Tips, Home Buyer, FloridaPublished August 28, 2026
Will Mortgage Rates Drop? Should You Wait to Buy in Sarasota?
Will Mortgage Rates Drop? Should You Wait to Buy in Sarasota?
By Traci Bolen | Sand Sea Homes | eXp Realty Serving Sarasota, Manatee, and Charlotte County
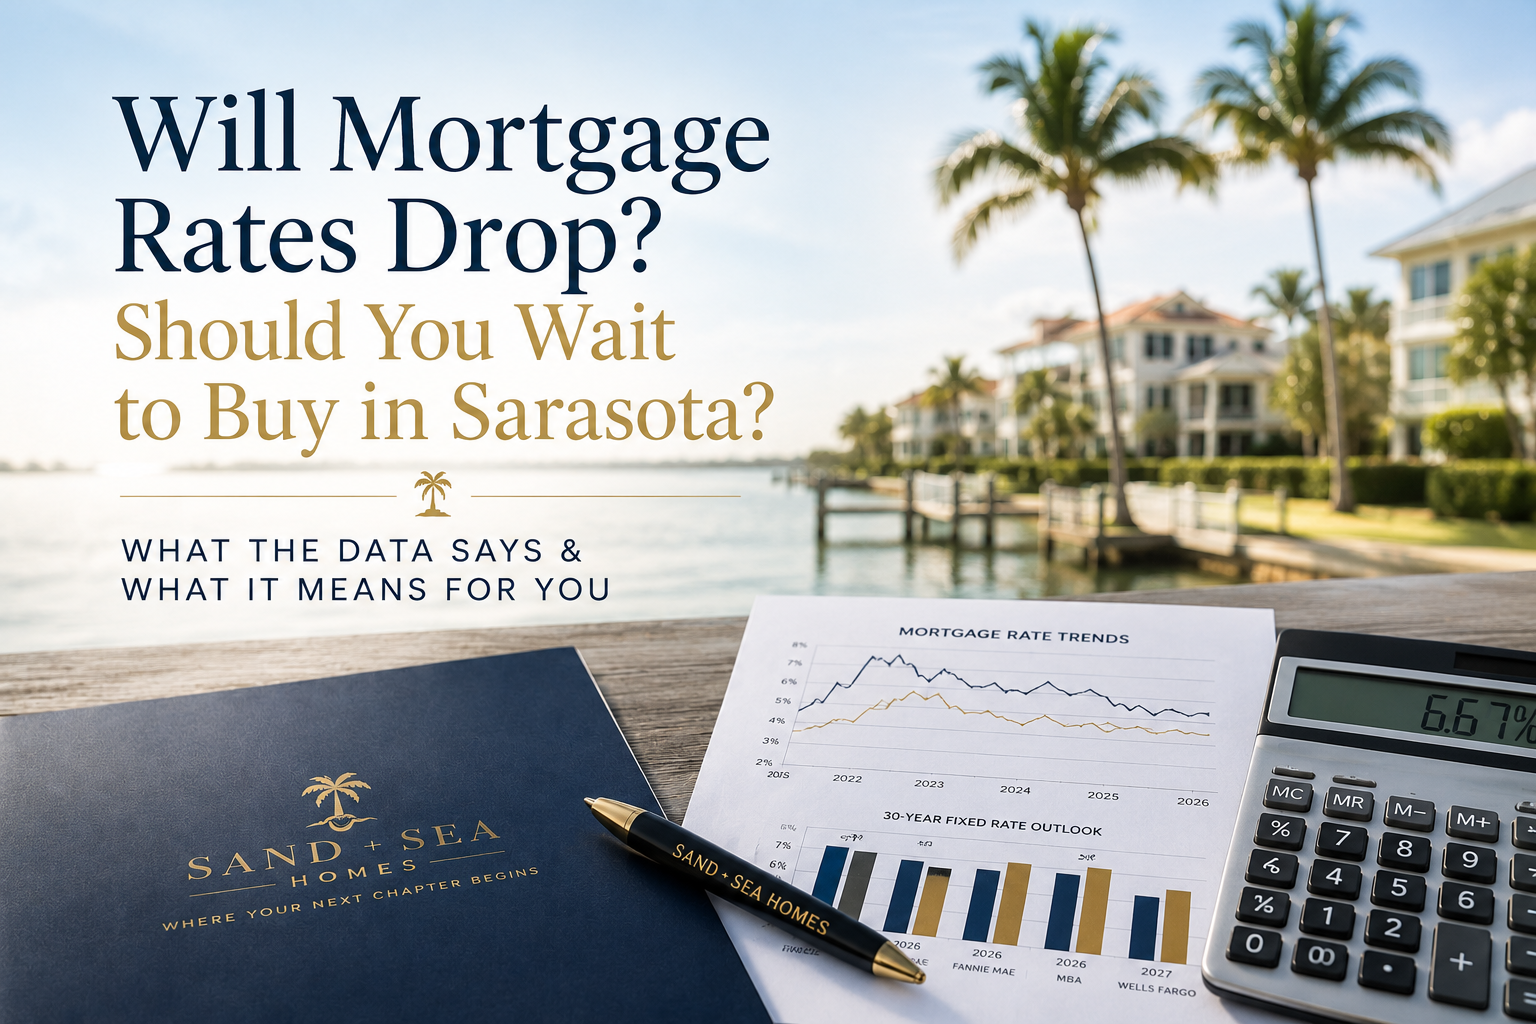
Probably not by much, and not soon. As of Freddie Mac's most recent report, the 30-year fixed averaged 6.67% in mid-August 2026, and the major forecasters, Fannie Mae, the Mortgage Bankers Association, and Wells Fargo among them, mostly expect rates to stay in the mid-6% range through the rest of this year, with any real relief pushed into 2027. If you're holding off on buying a Sarasota home specifically because you're waiting for a rate in the 5s, here's the actual math on what that wait is likely to cost you.
Where Rates Actually Stand Right Now
Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed at 6.67% and the 15-year fixed at 5.96% as of mid-August 2026. That's held in a fairly narrow band, roughly 6.2% to 6.8%, for most of the year. The Federal Reserve cut its benchmark rate three times in 2025, but has paused at every meeting so far in 2026, including its most recent one in late July, as it waits to see how prior cuts work through the economy.
Forecasts for where things go from here genuinely disagree, which is worth being honest about. Fannie Mae's August outlook has the 30-year fixed sitting near 6.8% through the end of 2026 and staying close to that through 2027. The Mortgage Bankers Association projects a similar mid-6% range persisting into 2027. On the more optimistic end, Morgan Stanley's strategists see a path to the mid-5% range by mid-2026 if the 10-year Treasury yield eases as they expect, though they also flag rates likely climbing back up in the back half of the year. The honest summary: nobody credible is forecasting a return to 3% or 4% rates, and most forecasters put any meaningful easing into 2027 rather than this year.
The Math on Waiting
Here's the trade-off that's easy to underweight when you're focused on the rate alone. Say a $450,000 home doesn't move in price for six months while you wait for a rate improvement. If rates ease by a modest 0.25 point in that time, your monthly payment on a $360,000 loan drops by roughly $55 to $60. That's real money.
But according to RASM's July 2026 report, Sarasota County single-family home prices are up 5.0% year-over-year, and Manatee County is up even more. If that pace continues, or even slows somewhat, a $450,000 home today could reasonably cost $10,000 to $20,000 more in six to twelve months. A rate saving of $55 a month doesn't come close to offsetting a purchase price that's $15,000 higher before you've even started paying down principal. This is the same dynamic that's played out nationally for the past several years: a majority of would-be buyers who held off in 2025 waiting for lower rates didn't get them, and the homes they were looking at got more expensive in the meantime.
None of this means rates don't matter. It means the rate is one input in a two-part equation, and the other input, local home prices, has been moving in a direction that argues against waiting indefinitely for the first one to improve.
"Marry the House, Date the Rate"
This is a common phrase in the industry for a reason: your purchase price and the home itself are fixed once you close, but your rate isn't. If you buy now at 6.67% and rates genuinely do ease to the 6% range or lower in 2027, refinancing is a standard, well-understood process that doesn't require you to have timed anything perfectly. You lock in today's price and today's inventory conditions, and you keep the option open to refinance later if the opportunity shows up.
The buyers who come out ahead in a market like this generally aren't the ones who guessed correctly on rate timing. They're the ones who bought a home that worked for their life and budget at a payment they could genuinely afford, and treated any future rate drop as a bonus, not a plan.
What This Looks Like in Sarasota Specifically
According to RASM's July 2026 data, single-family inventory in Sarasota County fell 23.4% year-over-year, pulling months of supply down to 3.9, solidly in seller's-market territory, with homes closing at 94.2% of original list price. Manatee County looks similar, with 4.1 months of supply. That tightening inventory is a big part of why prices have kept climbing even with rates well above pandemic-era lows: there simply isn't enough supply to soften pricing the way more balanced markets are seeing nationally.
Condos are a different story, with 5.6 months of supply in Sarasota County, closer to balanced, and buyers taking a median of 92 days to go under contract rather than rushing. If you're rate-sensitive and have some flexibility, the condo segment currently offers more room to negotiate and less pressure to act before you're ready, compared to the tighter single-family market.
When Waiting Does Make Sense
To be fair to the other side of this: waiting is the right call if your own finances aren't ready, not because of what the Fed might do. If you need more time to save a larger down payment, improve your credit, pay down other debt, or simply aren't confident in your job stability over the next year or two, those are real reasons to wait that have nothing to do with guessing at rate movements. A rate forecast, even a confident one, is still a forecast. Your own financial readiness is something you actually control.
Should You Wait for Rates to Drop?
Based on where forecasters currently stand, waiting for a dramatically lower rate this year is unlikely to pay off, and in a market where local inventory is tight and prices are still climbing, the cost of that wait typically shows up in a higher purchase price rather than in savings. If you're financially ready and you find a home that fits, buying now and treating a future refinance as a bonus is the stronger play than holding out for a number that most forecasters don't expect to see until 2027, if then.
Want to run the actual numbers on what waiting versus buying now looks like for your specific budget? Schedule a consultation with Traci today.
Sand Sea Homes | eXp Realty | Serving Sarasota, Manatee, and Charlotte County
#SarasotaRealEstate #MortgageRates #ShouldIWaitToBuy #SarasotaHousingMarket #GulfCoastRealEstate #ManateeCountyRealEstate #CharlotteCountyHomes #SandSeaHomes #TraciBolen #eXpRealty #ItMattersWhoYouHire #FloridaRealEstate #HomeBuyerTips
Traci Bolen
Owner / Realtor | Sand + Sea Homes
or another way