Categories
Home Buyer, Home Seller, FloridaPublished October 22, 2026
Low Appraisal in Sarasota? What Happens If the Home Appraises Lower Than the Offer
By Traci Bolen | Sand Sea Homes | eXp Realty
Serving Sarasota, Manatee, and Charlotte County
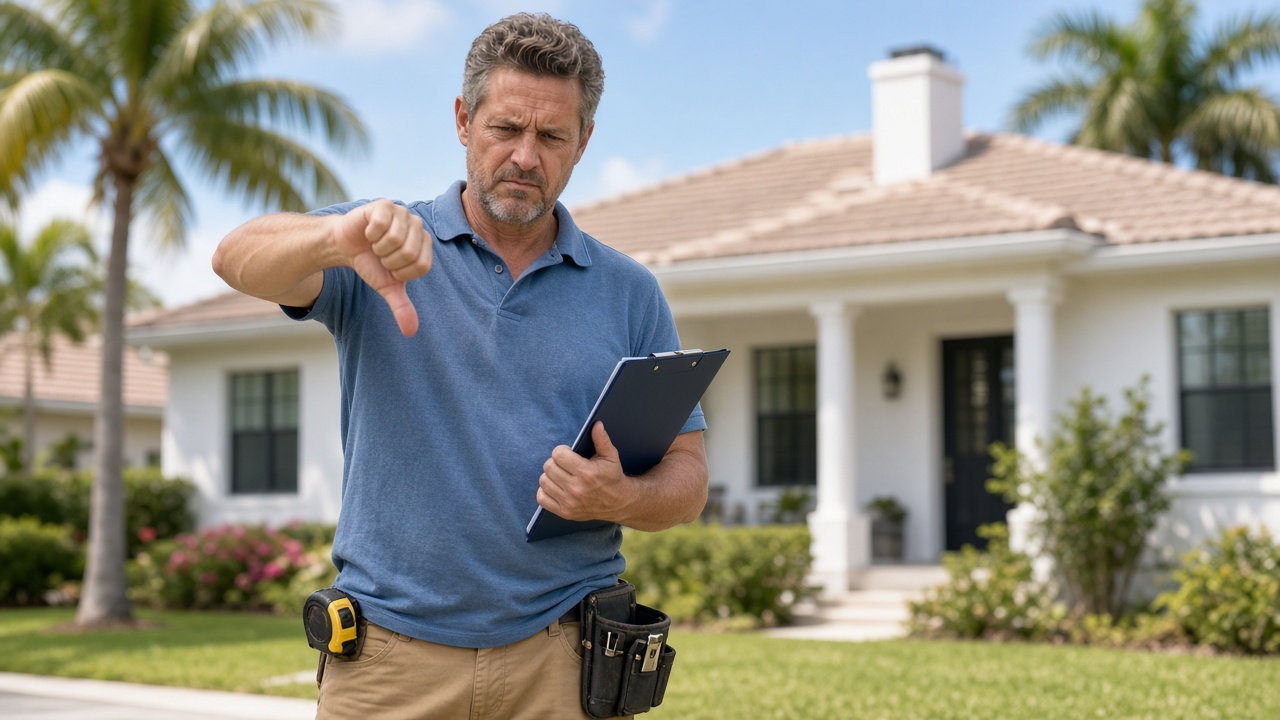
Your offer was accepted, the inspection went fine, and then the lender calls to say the appraisal came in under the contract price. A low appraisal in Sarasota doesn't automatically end the deal, but it changes the math for both sides. Whether you're buying in Lakewood Ranch or selling in Venice, here's what happens next and what your Florida contract says.
Quick Answer
If a home appraises below the offer, the lender generally won't lend on the higher price, which leaves an "appraisal gap." Buyers and sellers can renegotiate the price, split the difference, have the buyer cover the gap in cash, challenge the appraisal with better comps, or cancel if the contract allows it. Under Florida's standard FR/BAR contracts, whether a buyer can walk away and keep the deposit depends on the financing terms and riders in the contract, so read them before you sign.
Why a Low Appraisal Matters
Lenders size the loan using the lower of the purchase price or the appraised value. If you agree to $500,000 and the home appraises at $475,000, the lender works from $475,000, and the $25,000 gap has to be covered some other way.
Common reasons appraisals come in low:
- An optimistic list price, or upgrades valued higher than the market will pay.
- Multiple offers that pushed the price above recent sales.
- A shifting market, where older comps don't reflect today's prices.
- Appraiser errors, like wrong square footage, a missed pool, or comps from a different neighborhood.
Homes here vary a lot by neighborhood. A newer Lakewood Ranch home, a waterfront ranch in Bradenton, and a canal home in Port Charlotte or Punta Gorda all have very different comps.
What Florida's FR/BAR Contract Says About a Low Appraisal in Sarasota
Most local deals use the Florida Realtors/Florida Bar (FR/BAR) contracts. One detail surprises buyers: according to Florida Realtors, the financing contingency does not give you a built-in right to cancel just because the home appraised below the price.
The Financing Contingency (Paragraph 8)
Here, "Loan Approval" includes an appraisal the lender is satisfied with, if it requires one. The test isn't whether the appraisal hits the price; it's whether the lender will still make the loan in the contract. Florida Realtors' legal team explains that if the lender says the value isn't enough, the buyer can cancel before the Loan Approval Period ends. If the lender will still fund, that part is satisfied. The Loan Approval Period defaults to 30 days if left blank, and the buyer's notices have to be in writing.
The Appraisal Contingency Rider (Rider F)
For a clear exit, add the Appraisal Contingency rider. It sets a deadline and a value, usually the price. If the appraisal falls short, the buyer can cancel without penalty or proceed anyway.
FHA and VA Loans
FHA and VA buyers get extra protection. The FR/BAR FHA/VA rider includes language that overrides the rest of the contract, so the buyer isn't obligated to close and shouldn't lose the deposit if the appraised value falls short of the required amount. For VA loans, the VA Escape Clause is required in every purchase contract. It lets the buyer back out without penalty if the price exceeds the VA's "reasonable value," or still go ahead if they choose to.
Your Options When the Appraisal Comes In Low
1. Renegotiate the Price
The appraisal is real evidence of value, and the next buyer's lender would likely see a similar number, so sellers often agree to at least some reduction.
2. Split the Difference
The seller comes down partway and the buyer brings extra cash for the rest.
3. The Buyer Covers the Gap
If you have the savings, you can pay the difference. Just know you'll start with less equity, which matters more if you might sell within a few years.
4. Challenge the Appraisal
Get your copy of the report and check it for factual mistakes. Fannie Mae describes a formal "reconsideration of value" (ROV) that you request through the lender. Communication goes through the lender, since the appraiser's client is the lender. Federal regulators note at HelpWithMyBank.gov that a lender can ask the appraiser to look at other comps, explain their reasoning, or fix factual errors, and can choose to order a second appraisal.
5. Walk Away
If your contract gives you an exit (Loan Approval not met, Rider F, or the FHA/VA clauses), you can typically cancel and recover your deposit by meeting deadlines and giving written notice. Without that protection, walking away could cost the deposit.
Tips for Buyers
- Decide on appraisal protection before you write the offer, including whether Rider F fits.
- Set a gap budget. Offering to cover a capped amount can strengthen an offer, but only promise cash you'd be comfortable spending.
- Watch deadlines so the appraisal arrives well before the Loan Approval Period ends.
- Know your cash to close. Our guide to seller concessions explains how credits can help.
Tips for Sellers
- Price from real comps. Start with what your home is worth right now.
- Prepare an upgrade list (roof year, impact windows, HVAC, pool equipment, permitted improvements) for your agent to share.
- Don't refuse by reflex. The next buyer's appraisal may land in the same place, after weeks back on the market.
- Weigh offers carefully. A slightly lower offer with gap coverage may beat the highest price.
The Bottom Line
A low appraisal is usually a negotiation, not the end of the deal. Know your contract terms, plan for a gap, and lean on solid neighborhood comps.
Writing an offer or getting ready to list and want a plan in case the appraisal comes in low? We'll walk you through your contract options and pull the comps for your neighborhood. Schedule a consultation with Traci today.
Frequently Asked Questions
Can a seller be forced to lower the price after a low appraisal?
No. The seller can lower the price, offer a credit, or refuse. The buyer then decides whether to cover the gap or cancel, if the contract allows.
Do I get my deposit back if the home appraises low in Florida?
It depends on your contract. You're generally protected if the lender won't approve the loan within the Loan Approval Period, if you used Rider F, or under the FHA/VA rider. Otherwise, your deposit may be at risk.
How do I dispute a low appraisal?
Request a reconsideration of value through your lender, pointing out factual errors and recent comparable sales from the same neighborhood.
Does a low appraisal matter if I'm paying cash?
No lender means no required appraisal, though cash buyers can still order one and use an appraisal contingency.
What is an appraisal gap clause?
It's an offer term where the buyer agrees to cover some or all of a shortfall, often up to a set dollar amount. It strengthens an offer, but the buyer needs the cash to back it.
Sand Sea Homes | eXp Realty | Serving Sarasota, Manatee, and Charlotte County
#SarasotaRealEstate #LowAppraisal #AppraisalGap #FloridaRealEstate #SandSeaHomes #TraciBolen #eXpRealty #GulfCoastRealEstate #ManateeCountyRealEstate #CharlotteCountyHomes #HomeBuyerTips #HomeSellerTips
Traci Bolen
Owner / Realtor | Sand + Sea Homes
or another way