Categories
Home Buyer, Buyer TipsPublished October 26, 2026
Pre-Qualification vs Pre-Approval in Sarasota: Which One Do You Need to Buy a Home?
By Traci Bolen | Sand Sea Homes | eXp Realty
If you're getting ready to buy a home in Sarasota, one of the first questions you'll run into is the difference between pre-qualification vs pre-approval in Sarasota and which one you actually need. The two terms get tossed around like they mean the same thing, but they don't carry the same weight with sellers. Knowing the difference can save you time, protect your credit, and make your offer stand out in Lakewood Ranch, Venice, Bradenton, and across Manatee and Charlotte County.
Quick Answer
A pre-qualification is a fast, informal estimate of what you might be able to borrow, usually based on information you report yourself and often with only a soft credit check. A pre-approval is a deeper review where a lender verifies your income, assets, debts, and credit, then issues a letter for a specific loan amount. In Sarasota, most listing agents expect to see a pre-approval letter with any financed offer.
Pre-Qualification vs Pre-Approval in Sarasota: The Key Differences
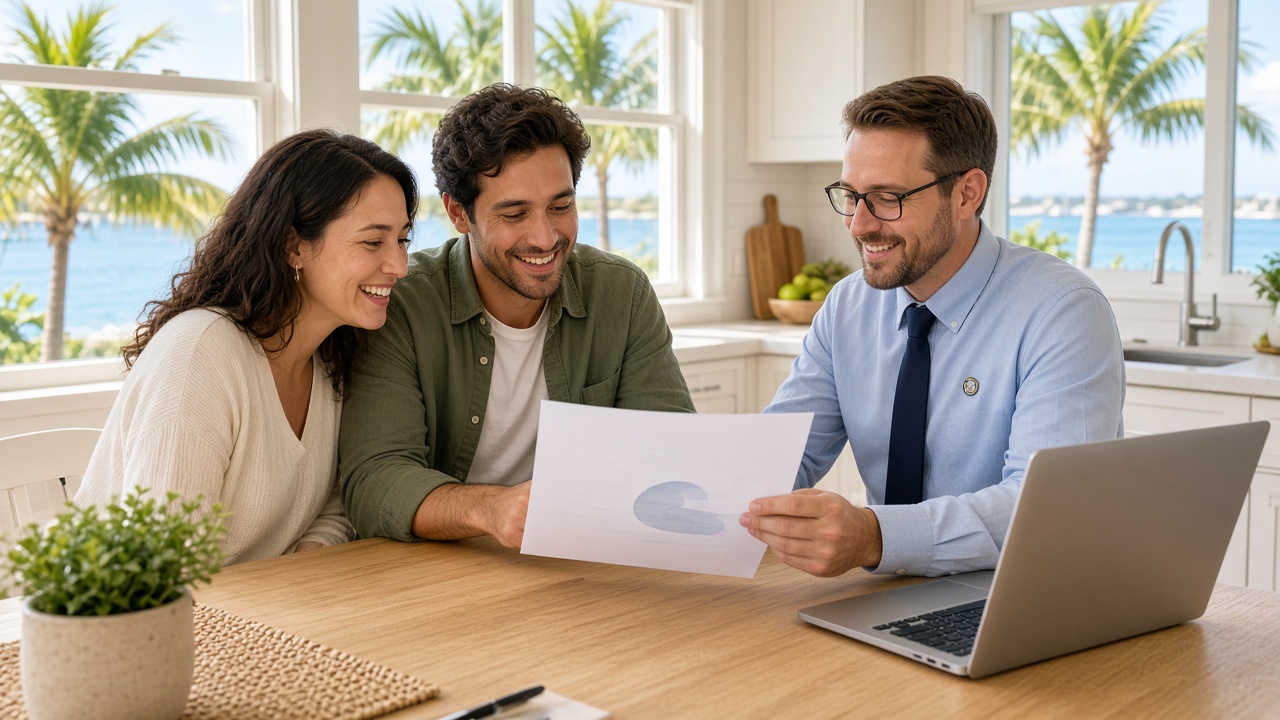
The biggest difference is verification. With a pre-qualification, the lender takes your word for your income, savings, and debts. With a pre-approval, the lender asks for proof and checks it. That one step changes how sellers and their agents view your offer.
What a pre-qualification looks like
- Often done online or over the phone in minutes
- Based mostly on self-reported income, assets, and debts
- Usually a soft credit pull, which doesn't affect your score
- Gives a rough price range and estimated monthly payment
What a pre-approval looks like
- You submit documents such as pay stubs, W-2s or tax returns, and bank statements
- The lender typically runs a full credit check
- You get a letter showing a loan amount and likely loan programs (conventional, FHA, VA, and so on)
- It can take anywhere from a day to several days, depending on how quickly you provide paperwork
One helpful note from the Consumer Financial Protection Bureau: lenders don't all use these words the same way. Some call a verified letter a "pre-qualification," and others call an unverified one a "pre-approval." What matters is what the lender actually checked, so ask them directly.
Why Sarasota Sellers Care About Pre-Approval
Sellers want to know that if they take their home off the market for you, your financing is likely to hold up through closing. A verified pre-approval letter tells them a lender has already looked under the hood. That's especially important here, where many buyers compete against cash offers from retirees, second-home buyers, and investors relocating to Southwest Florida.
When a seller is comparing two similar offers, the one backed by a solid pre-approval (and a lender who answers the phone) often wins. In some Lakewood Ranch and west-of-Trail Sarasota neighborhoods, listing agents won't even schedule a second showing without one.
When to Get Each One
A pre-qualification is great when you're just starting to explore, maybe browsing Venice condos or comparing Bradenton and Parrish new construction, and you want a ballpark budget. Once you're ready to tour homes seriously and write offers, it's time to get pre-approved.
Getting pre-approved early has another benefit: it can surface credit or documentation issues while there's still time to fix them, instead of in the middle of a contract.
Florida-Specific Things to Factor In
A pre-approval amount is not the same as a comfortable budget. In Sarasota and Manatee County, your monthly payment includes more than principal and interest. Make sure your lender is estimating:
- Homeowners insurance, which can vary widely by age of roof, construction type, and distance from the coast
- Flood insurance if the home sits in a flood zone, which many lenders will require
- Property taxes, based on the new purchase price rather than the seller's current bill, since the seller's homestead savings don't transfer to you
- HOA or CDD fees, common in Lakewood Ranch, North Port, and many newer communities
Ask your lender to run numbers using real insurance quotes and realistic taxes for the specific area you're shopping in. That keeps your pre-approval grounded in what you'll actually pay.
Tips to Make Your Pre-Approval Work for You
- Gather documents up front. Two years of W-2s or tax returns, recent pay stubs, two months of bank statements, and ID speed things up. Self-employed buyers should expect to provide more.
- Shop lenders within a short window. Credit scoring models generally treat multiple mortgage inquiries within about 45 days as one, so you can compare offers without extra damage to your score.
- Don't change your finances. Avoid new credit cards, car loans, job changes, or large unexplained deposits between pre-approval and closing.
- Watch the expiration date. Many pre-approval letters are good for roughly 60 to 90 days. If your search runs longer, ask your lender to refresh it.
- Request a letter for each offer. A letter tailored to the offer price keeps you from revealing your full maximum to the seller.
- Remember it's not a guarantee. Final approval still depends on underwriting, the appraisal, and your finances staying the same.
How Sand + Sea Homes Can Help
We work with buyers every day across Sarasota, Manatee, and Charlotte County, and we can connect you with trusted local lenders who understand Florida insurance, flood zones, and condo rules. If you're thinking about buying, reach out to Sand + Sea Homes at (941) 352-2121 or visit sandseahomes.com. We'll help you get pre-approved the right way and find a home that fits your life and your budget.
Frequently Asked Questions
Is pre-approval required to make an offer in Sarasota?
It isn't legally required, but most Sarasota and Manatee listing agents expect a pre-approval letter with any financed offer, and many sellers won't seriously consider an offer without one.
Does getting pre-approved hurt my credit score?
A pre-approval often involves a hard credit inquiry, which may lower your score slightly for a short time. Comparing several lenders within about 45 days generally counts as a single inquiry.
How long does a mortgage pre-approval last?
Many pre-approval letters are valid for about 60 to 90 days. If your home search takes longer, your lender can update your documents and reissue the letter.
Can I be denied a loan after being pre-approved?
Yes. Pre-approval is not a final loan commitment. A low appraisal, a change in income, new debt, or problems found in underwriting can still affect your loan.
Is pre-qualification enough when buying a home in Florida?
Pre-qualification is fine for early budgeting, but once you're ready to tour homes and write offers in Sarasota, Lakewood Ranch, Venice, or Bradenton, a verified pre-approval will make your offer far more competitive.
Traci Bolen
Owner / Realtor | Sand + Sea Homes
or another way